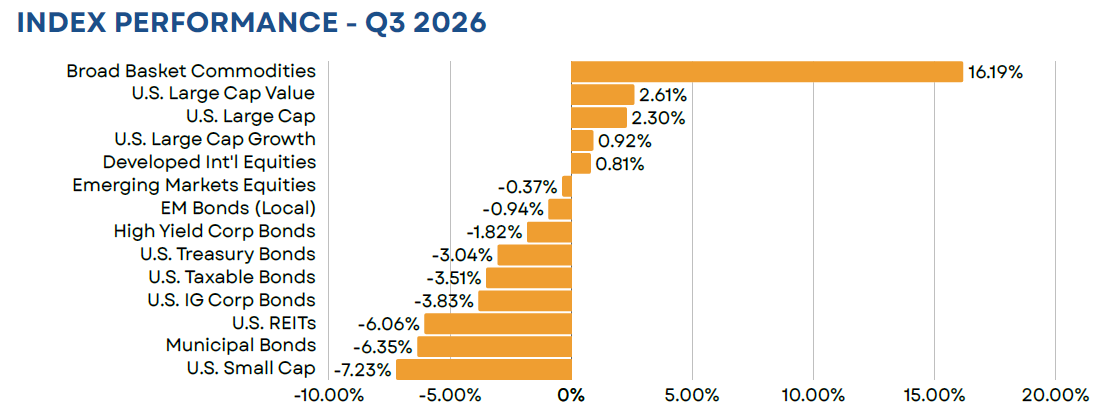
Despite a sharp rise in interest rates and renewed geopolitical tensions in the Middle East, global equities were generally positive during the third quarter. Strong corporate earnings, continued enthusiasm surrounding artificial intelligence, and a resilient U.S. economy helped offset growing concerns around inflation and higher energy prices. This led to a gain of 2.3% for the S&P 500. However, performance beneath the surface was considerably weaker, with small-cap stocks actually falling more than 7%. International equities also lagged, as the MSCI EAFE Index gained less than 1% and emerging markets declined modestly. Fixed income, however, was the clear laggard, as the Bloomberg U.S. Aggregate Bond Index fell roughly 3.5% amidst the backdrop of notably higher interest rates. Conversely, commodities were among the best performing asset classes, with the Bloomberg Commodity Index gaining over 16%, led by a sharp increase in energy prices.
Equity
Equity markets delivered positive returns during the quarter, although performance was increasingly concentrated among large-cap technology and AI-related companies. Although the S&P 500 gained 2.3%, just four names (Microsoft, NVIDIA, Apple, and Meta) contributed 4.2% to that total return figure. What this implies is that the remaining names in the index were actually net detractors from returns. In fact, of the roughly 500 names in the index, over 60% ended the quarter in negative territory. We also saw this theme flow through to small caps, with the Russell 2000 Index declining by more than 7%, highlighting the growing impact of higher interest rates on smaller, more economically sensitive companies.
Outside of the U.S., non-U.S. developed stocks posted positive results (+0.81% in USD-terms), underperforming their U.S. peers. Japan was a key contributor to the positive results, as rate increases from the BOJ led to strong gains in the currency. Conversely, emerging markets equities ended the quarter in negative territory (-0.37% in USD-terms). From a country standpoint, Korea was the largest detractor, as most of the market’s major AI players found themselves well into negative territory for the quarter. Most notably, SK Hynix which accounts for nearly 6% of the MSCI EM Index, declined by more than 20%.
Fixed Income
Fixed income markets faced significant pressure during the third quarter as inflation concerns and rising energy prices caused investors to reassess their outlook for monetary policy. The Bloomberg U.S. Aggregate Bond Index declined approximately 3.5%, marking a difficult quarter for core bonds. The 10-year Treasury yield rose from roughly 4.46% at the end of June to 5.29% by quarter-end, while the 30-year yield climbed above 5.6%, reaching its highest level in more than two decades. This all came on the back of a dramatic change in investor expectations for the future path of rates. Entering the year investors were pricing in multiple cuts by the end of 2026. That expectation is now a total of two 25bps hikes, one of which we received from the Fed in September.
Treasuries were not the only fixed income asset class to experience losses in Q3. Credit markets also weakened as the sharp increase in treasury yields weighed on the confidence of investors. Spreads had been tight and stable for much of the last six months, with high yield bonds trading at just 270 bps on average over treasuries. This measure jumped to more than 300 bps by month the end.
Real Assets
Real assets were among the strongest performers during the third quarter, driven primarily by a dramatic increase in energy prices. The Bloomberg Commodity Index gained approximately 16%, with oil and natural gas leading the advance. WTI crude rose roughly 30% during the quarter, finishing near $90 per barrel, as an escalation in the Iran conflict increased concerns about disruptions to Middle Eastern energy supplies. Brent crude experienced a similar surge, briefly moving above $105 per barrel. Precious metals were more mixed. Gold gained approximately 3% for the quarter, despite falling more than 6% in September as sharply higher yields and a stronger dollar pressured the metal.
Closed End Funds
Closed-end funds experienced increased volatility during the quarter as rising interest rates and widening credit spreads pressured both underlying fixed-income portfolios and fund market prices. The average discount across closed-end fund sectors reached more than 7% at the end of September, roughly 200 bps wider than where they began the quarter. The deterioration was particularly noticeable among taxable fixed-income funds, where discounts gapped out to nearly 8.5%, the most attractive levels we’ve seen since late 2022.
iCM Strategy Performance
iCM’s Tactical strategies, which utilize ETFs and/or mutual funds, performed well on an absolute and relative basis versus their benchmarks. Our fixed income strategy was largely supported by our allocation to emerging markets local bonds. The asset class finished the quarter in negative territory but outperformed U.S. investment grade bonds by more than 250 bps. Within the equity strategy, our overall allocation to global value stocks was a strong contributor. Despite mega-cap hyperscalers driving much of the market’s performance during the quarter, value stocks outperformed in both U.S. and international markets. This was particularly true within the emerging space, where an underweight to volatile Korean markets led to relative outperformance.
iCM’s Tactical Income strategies, which include TICE and TAO, saw mixed results on the quarter. TICE underperformed its benchmark as widening CEF discounts weighed on returns. The TAO strategies, however, performed well on a relative basis, buoyed by our holdings in non-U.S. value stocks.
Important Disclosures
Integrated Capital Management, Inc. is an SEC Registered Investment Advisor. Registration does not imply any certain level of skill or training. Monthly “Market Flash” is intended solely to report on various investment views held by Integrated Capital Management. Opinions, estimates, forecasts, and statements of financial market trends that are based on current market conditions constitute our judgment and are subject to change without notice. We believe the information provided here is reliable but should not be assumed to be accurate or complete. References to specific securities, asset classes and financial markets are for illustrative purposes only and do not constitute a solicitation, offer or recommendation to purchase or sell a security.
Past performance is no guarantee of future results. Please note that investments in foreign markets are subject to special currency, political, and economic risks. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index. Asset Allocation Outlook is intended solely to report on various investment views held by Integrated Capital Management. Opinions, estimates, forecasts, and statements of financial market trends that are based on current market conditions constitute our judgment and are subject to change without notice. We believe the information provided here is reliable but should not be assumed to be accurate or complete. References to specific securities, asset classes and financial markets are for illustrative purposes only and do not constitute a solicitation, offer or recommendation to purchase or sell a security. Outlook may change at any time given shifting market conditions. Past performance is no guarantee of future results. Please note that investments in foreign markets are subject to special currency, political, and economic risks. Index performance returns do not reflect any management fees, transaction costs or expenses. Indexes are unmanaged and one cannot invest directly in an index.
Closed end funds are exchange traded, may trade at a discount to their net asset values and may deploy leverage. When the strategy purchases shares of a closed-end fund at a discount to its net asset value, there can be no assurance that the discount will decrease and may possibly increase. If a closed-end fund uses leverage, increases and decreases in the value of its share price may be magnified. Distributions by a closed-end fund may include a return of capital, which would reduce the fund’s net asset value and its earnings capacity. Closed end funds are offered by prospectus. The prospectus and/or other applicable offering documents contain this and other important information about the investment strategy. You should read the prospectus and/or other applicable offering documents carefully before investing. Investors should consider the investment objectives, risks, charges and expenses of the investment strategy before investing. iCM uses third-party data that is believed to be accurate and complete. All data is subject to change. All investing involves the assumption of risk and the possible loss of principal. The main risks as it pertains to iCM’s strategies are US equity risk, international equity and fixed-income market risk, interest rate risk and currency risk. While attempting to achieve the objectives of the strategies, investors will be exposed to the risk of loss from these sources along with others yet to be identified.
TICE Blended Benchmark comprised of 32% S&P 500/8% MSCI EAFE/38% Bloomberg Aggregate Bond/20% Bloomberg Municipal Bond/2% Cash
iCM TICE Alpha Opportunities Benchmarks:
TAO 35/65‐Blended Index: 26.25% Russell 3000/8.75% MSCI EAFE/63% Bloomberg Aggregate Bond/2% Cash
TAO 50/50‐Blended Index: 37.5% Russell 3000/12.5% MSCI EAFE/48% Bloomberg Aggregate Bond/2% Cash
TAO 60/40‐Blended Index: 45% Russell 3000/15% MSCI EAFE/38% Bloomberg Aggregate Bond/2% Cash
TAO 80/20‐Blended Index: 60% Russell 3000/20% MSCI EAFE/18% Bloomberg Aggregate Bond/2% Cash
iCM Income Opportunities Benchmark: Blended Index: 7.50% Russell 3000/2.50% MSCI EAFE/88% Bloomberg Aggregate Bond/2% Cash
Index Definitions
FTSE NAREIT All Equity REITs TR = U.S. REITs
S&P 500 Index = U.S. Large Cap
Russell 1000 Growth TR = U.S. Large Growth
Russell 1000 Value TR = U.S. Large Value
Russell 2000 Index = U.S. Small Cap
MSCI EAFE ND USD = Developed International Equities
Bloomberg High Yield Corp Bond = High Yield Bonds
Bloomberg Municipal TR = Municipal Bonds; BBgBarc
Bloomberg US Credit TR = U.S. IG Corp Bonds
Bloomberg Aggregate Bond = U.S. Taxable Bonds
Bloomberg Treasury TR = U.S. Treasury Bonds
MSCI Emerging Markets ND USD = Emerging Markets Equities;
JPM GBI EM Glbl Divers TR = EM Bonds;
Bloomberg Commodity TR USD = Broad Basket Commodities
First Trust Composite Closed-End Fund TR Index = Closed End Funds
(MMXXVI)